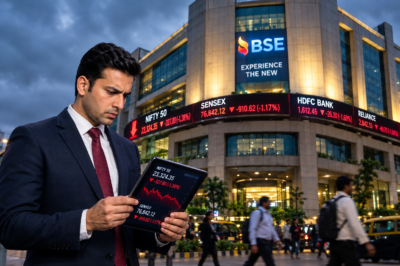
The Indian stock market is going through a period of heightened uncertainty, with the Nifty 50 closing below the important 23,350 level. The decline reflects more than a routine market correction, as persistent selling pressure, weakening technical indicators and global economic concerns have combined to affect investor sentiment. The Sensex also remained under pressure, highlighting the broader cautious mood prevailing across Dalal Street.
The recent weakness follows several weeks of sustained selling after a prolonged period of strong market performance. Earlier optimism, supported by corporate earnings and expectations of continued economic growth, had pushed valuations of several sectors to elevated levels. The present correction can therefore be viewed partly as an adjustment between market valuations and underlying fundamentals. However, the pace of the decline has raised concerns among investors.
Technical Indicators Signal Continued Weakness
From a technical perspective, 23,350 had emerged as an important support zone for the Nifty. Its breach has increased selling pressure and turned earlier support areas into potential resistance levels. The index has continued to form lower highs and lower lows, indicating a weakening market structure. Although the Relative Strength Index has entered oversold territory, the absence of a strong rebound suggests that selling momentum remains significant.
Market participants are also closely monitoring the 200-day Simple Moving Average, which is considered an important long-term technical indicator. A sustained decline below this level could indicate that the correction may become more prolonged.
Foreign Investors Remain a Major Source of Pressure
One of the key factors behind the market weakness has been continued selling by Foreign Portfolio Investors (FPIs). Strength in the US dollar and elevated US Treasury yields have made dollar-denominated assets comparatively attractive to international investors. Consequently, some global funds have shifted capital away from emerging markets.
The changing investment environment in China has also contributed to portfolio reallocation, with stimulus measures and relatively lower valuations attracting some international capital. Indian large-cap stocks, particularly those with high liquidity and substantial representation in the Nifty, have consequently experienced selling pressure.
Mixed Performance Across Sectors
The banking and financial services segment has remained under pressure amid concerns relating to Net Interest Margins and the pace of credit growth. The IT sector has displayed intermittent resilience, although uncertainties surrounding US immigration and outsourcing policies continue to influence sentiment.
The automobile sector has faced concerns over weaker-than-expected urban demand and rising dealership inventories. Meanwhile, defensive segments such as FMCG and pharmaceuticals have provided comparatively greater stability, although they too have been affected by the broader market correction.
Inflation, Currency and Interest Rates Add to Concerns
Domestic economic factors have further complicated the market outlook. Higher food prices and supply-side pressures have contributed to inflationary concerns, reducing expectations of an immediate interest-rate reduction by the Reserve Bank of India. Persistently high interest rates can increase borrowing costs and influence both corporate profitability and consumer spending.
At the same time, weakness in the Indian Rupee against the US Dollar has created additional challenges. While exporters may benefit from a weaker currency, imports—particularly crude oil—become more expensive, potentially adding to inflationary pressures. Currency movements, inflation and industrial activity therefore remain important factors for investors to monitor.
What Lies Ahead
A meaningful stabilisation of the market will depend on several factors, particularly a moderation in FPI outflows, changes in global bond yields and currency trends, and the performance of corporate earnings. The 23,000 level is being watched as another important psychological support area.
For investors with a long-term perspective, the correction may bring valuations closer to more sustainable levels, although market volatility remains significant. India’s longer-term economic prospects continue to be associated with demographic expansion, digitalisation and infrastructure development. Nevertheless, the immediate environment calls for greater attention to risk management, diversification, earnings visibility and fundamental strength.
As the market absorbs the prevailing domestic and global challenges, the focus is likely to remain on stability, corporate performance and macroeconomic developments before a clearer direction emerges.


Leave a Reply